Independent insurance guidance • Southeast Michigan
Serving clients in multiple states313-802-4910
Life insurance

Life insurance should match the people and responsibilities you are protecting.

Whether the goal is income replacement, family protection, debt coverage, legacy planning, or another need, Porchstone helps you understand available term and permanent life insurance options before you apply.

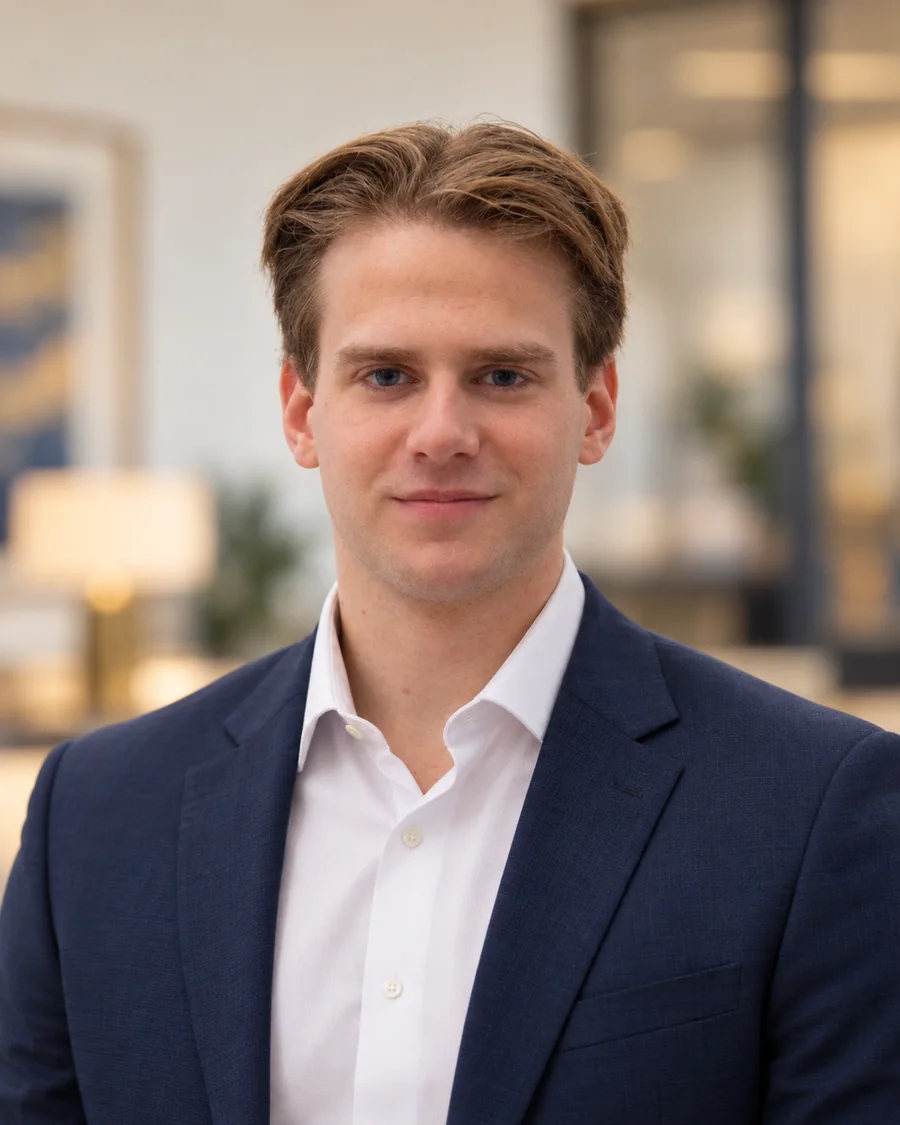
Levi Samborski, Founder and Principal of Porchstone Life Group

Coverage starts with the reason you need it

Life insurance is not one-size-fits-all. The appropriate amount and type of coverage depend on who relies on you, what financial obligations you want to protect, how long the need may last, your health and age, and the premium you can comfortably maintain.

Porchstone helps clients compare available options and understand the differences between temporary term coverage and permanent forms of life insurance.

Common reasons clients review life insurance

  • Replacing income for a spouse or children
  • Helping cover a mortgage or other major debts
  • Providing funds for final expenses
  • Leaving a legacy to family or another beneficiary
  • Reviewing older coverage after life circumstances change
  • Adding protection when existing employer coverage is not enough
Policy details matter. Premiums, underwriting, exclusions, cash-value features, lapse risk, and guarantees vary by product. An illustration is not the same thing as a guarantee unless the contract specifically identifies a value as guaranteed.

Compare first, apply second

The process starts by defining the need and reviewing the available choices. Levi can then help with the application process and remain your point of contact after coverage is issued.

Common questions

Questions worth asking before you decide.

What is the difference between term and permanent life insurance?

Term insurance is generally designed to provide coverage for a defined period. Permanent life insurance is designed to remain in force longer when required premiums and policy conditions are met, and some products may build cash value.

How much life insurance should I consider?

There is no single amount that fits everyone. Income, debts, dependents, existing assets, other insurance, and the purpose of the coverage all matter.

Will I need a medical exam?

That depends on the carrier, product, coverage amount, age, and underwriting. Some products may use accelerated or simplified underwriting while others may require additional medical information or an exam.

Can you review a policy I already have?

Yes. A review can help you understand the coverage you currently have and whether your needs have changed. Replacing existing life insurance can have disadvantages, so any replacement decision should be considered carefully.

Make the next step a conversation, not a commitment.

Tell Levi what you are trying to accomplish and get a clearer view of the options available to you.

Request a Personal Coverage Review